
Last updated September 23, 2026
Free visual inspection and a written scope of work before any mitigation begins - photos, moisture readings, and drying logs go in your claim file
The scope we write is the scope we bill. Anything new gets shown to you, in writing, before we touch it.
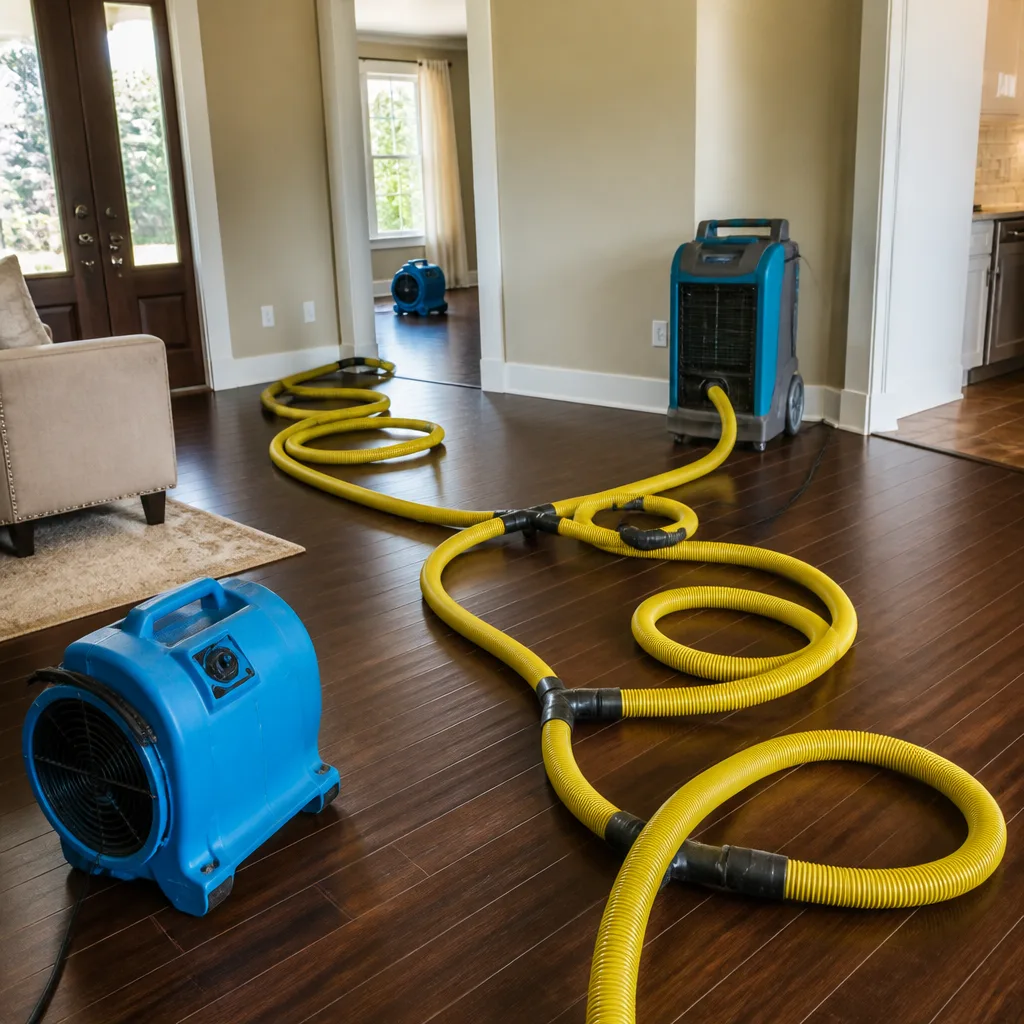
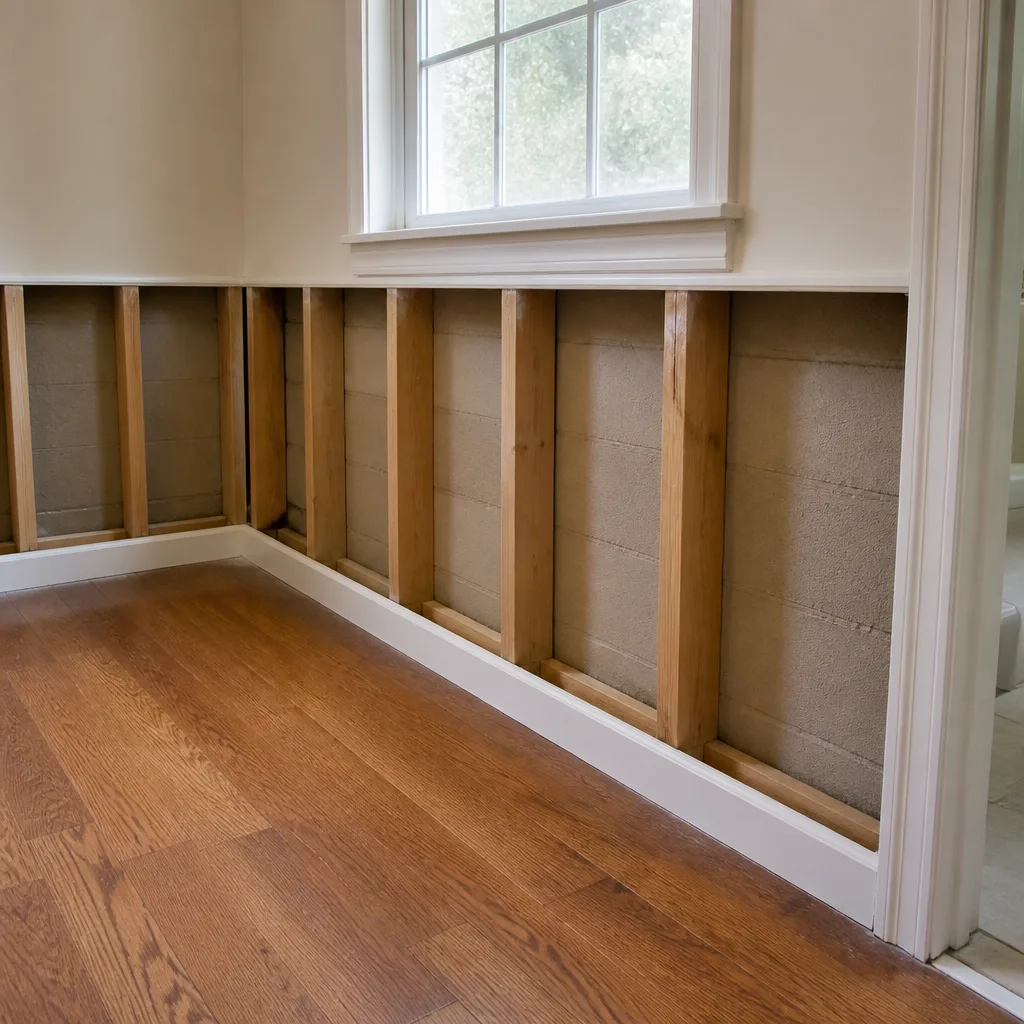
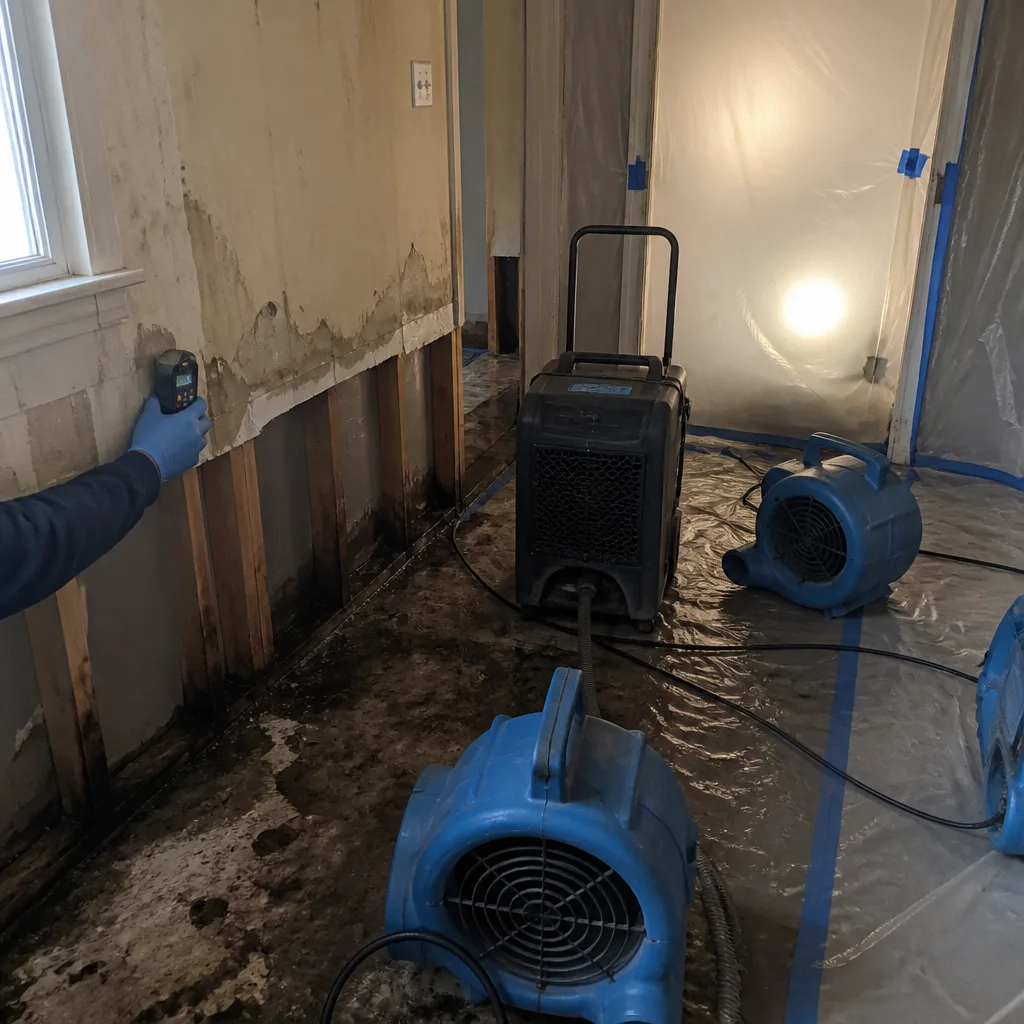 Before
 After
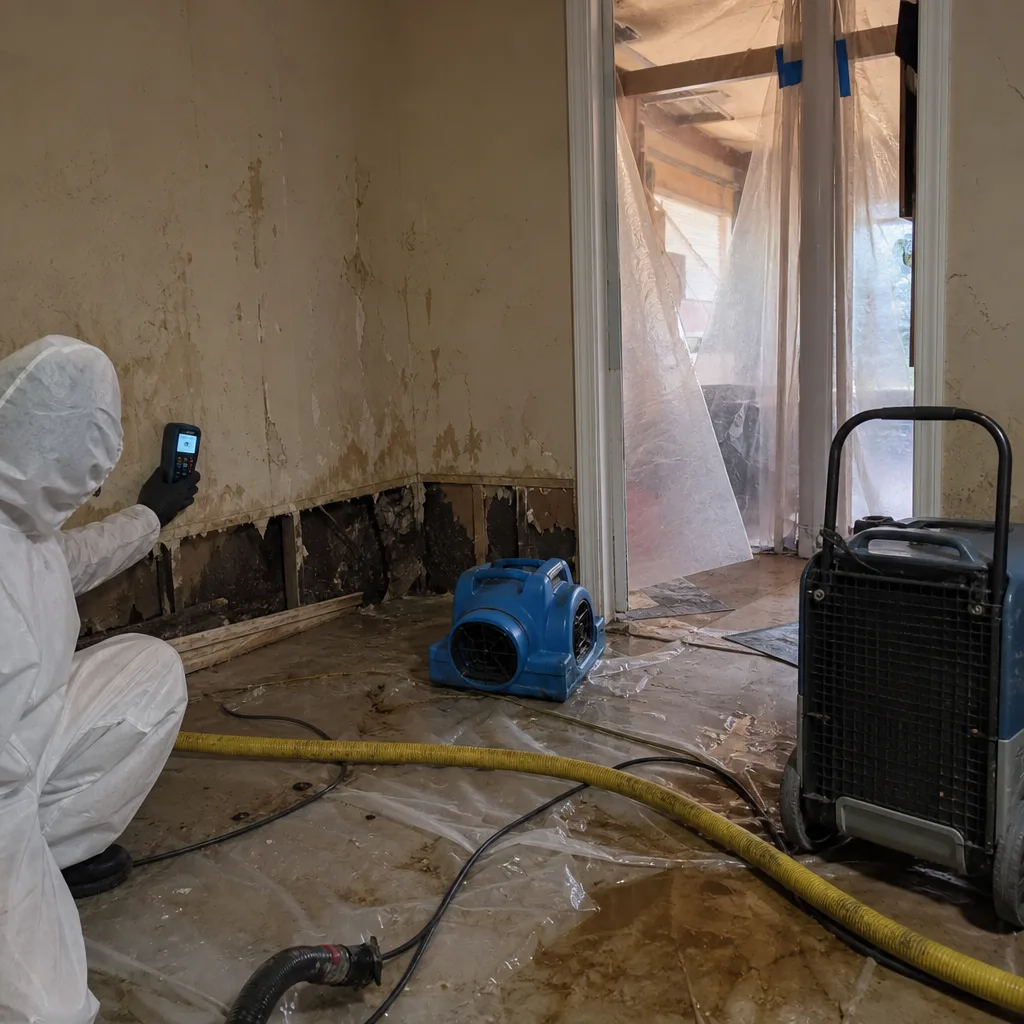 Before
 After
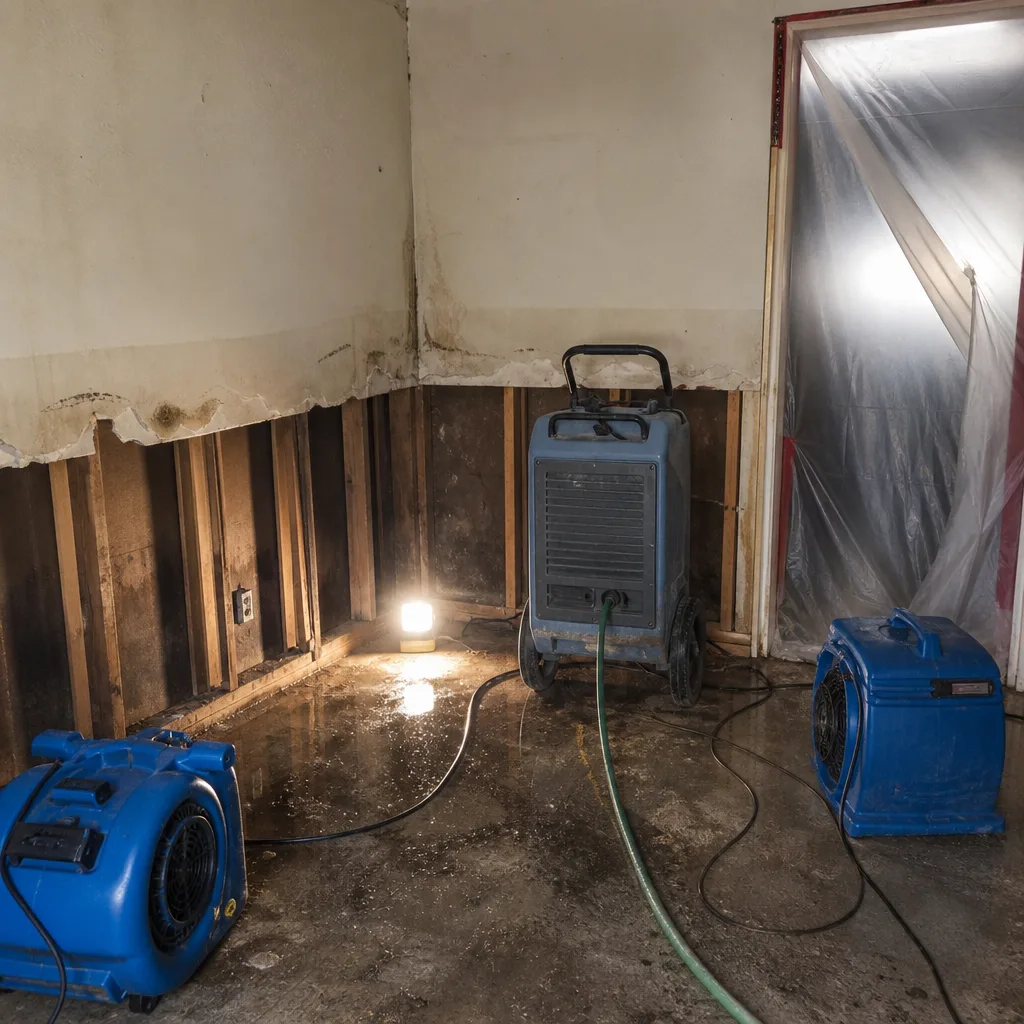 Before
 After
The Complete Guide to Damage Restoration in Bellflower
A water loss that should have paid out $18,000 gets settled at $6,200 - not because the damage was smaller, but because no one recorded a single moisture reading before the fans were pulled. In Bellflower, we’ve seen this exact scenario more than once. The 72 hours after damage begins is where claims are won or lost, and most homeowners don’t realize the decisions they make during that window are being judged by an adjuster they’ll never meet. This guide - alongside our Damage Restoration Warning Signs: A Bellflower Homeowner’s Reference Guide - maps every phase of a restoration project against the paper trail an adjuster will actually demand, so you keep the money you’re owed.
Quick Answer
Damage restoration in Bellflower is the process of returning a property to its pre-loss condition after water, fire, mold, storm, or biohazard damage. A properly documented restoration includes a written scope before work begins, room-by-room moisture readings, photo records on every visit, and equipment logs that justify every day of drying. Without this documentation, insurance claims are routinely reduced by 50% or more regardless of the actual damage.
Table of Contents
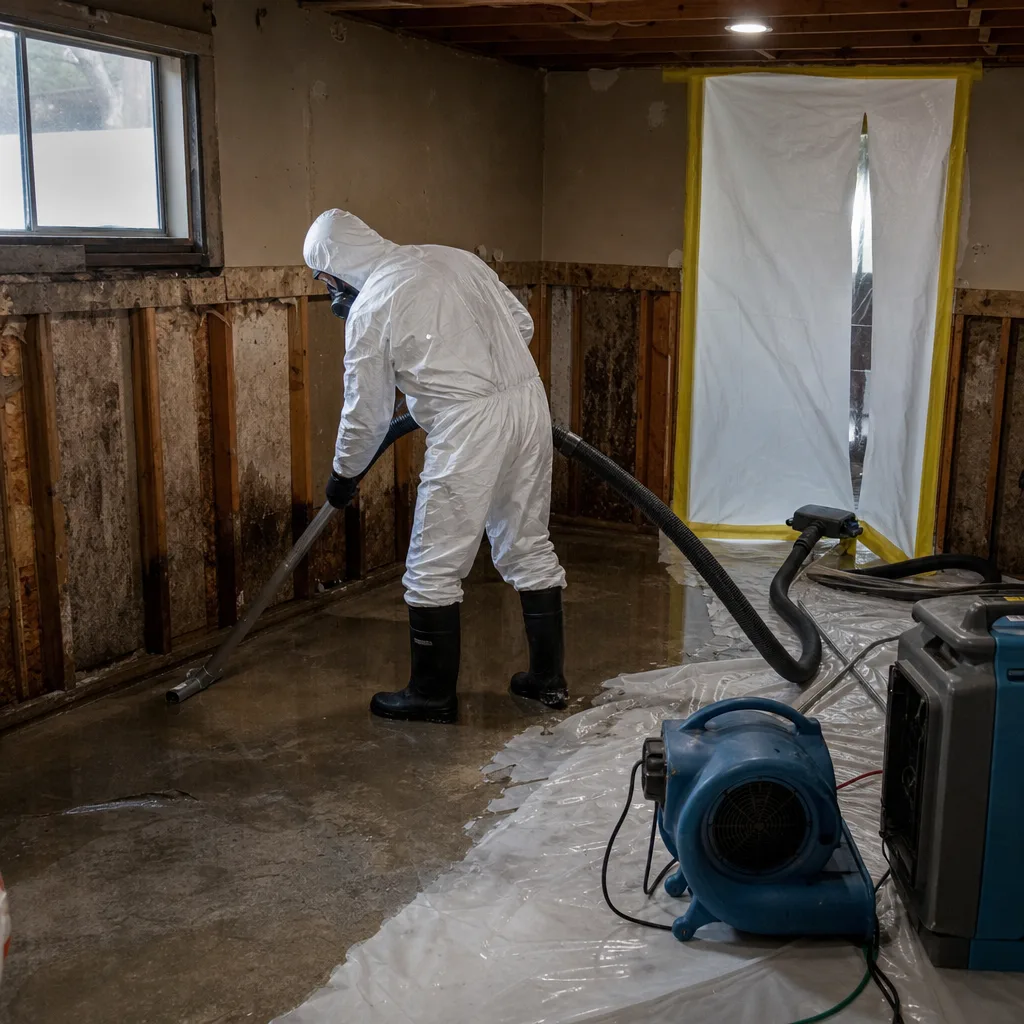
- The 72-Hour Documentation Window
- How Bellflower’s Geography Affects Your Claim
- Mitigation vs. Reconstruction: Why the Invoice Split Matters
- What a Compliant Drying Log Looks Like
- Cross-Referencing Your Scope Against Policy Language
- Equipment, Standards, and What They Mean for Your Documentation
- Common Mistakes to Avoid
- When to Call a Professional
- Frequently Asked Questions
 Before
 After
The 72-Hour Documentation Window
The first 72 hours after damage begins is not when most of the drying happens. It’s when most of the evidence disappears.
We’ve arrived at homes in Bellflower where well-meaning neighbors or the homeowner themselves have already torn out wet drywall, shop-vac’d the carpet, and set up box fans from the garage. The water is gone. So is any proof it was ever there in a form an adjuster will accept. No moisture readings. No photos of the original water line. No documentation of how far the water traveled horizontally through the wall cavity before it wicked up the insulation.
Here’s what must be documented before any equipment is moved or removed:
- Photograph the source and all affected materials while still wet. Take wide shots showing the room context, then close-ups of water lines on drywall, baseboard staining, and any visible mold growth. Date-stamp everything.
- Record moisture content readings on all affected and adjacent materials. Wood framing should be measured with a pin meter; drywall and subfloors with a non-invasive meter. Log readings in unaffected areas of the same structure for comparison. This establishes your baseline “dry standard.”
- Document the exact square footage of affected area by material type. Carpet over pad is one classification. Glued-down vinyl over concrete is another. Each carries different drying requirements and different per-square-foot pricing on Xactimate, the estimating platform most insurers use.
- Photograph equipment placement with serial numbers visible. Every dehumidifier, air mover, and axial fan should be logged. Adjusters verify equipment justification against psychrometric data - the measurement of temperature, relative humidity, and vapor pressure that proves drying progress.
- Establish a daily drying log before the first piece of equipment runs. This log must record: date, time, outdoor and indoor temperature, relative humidity, specific humidity readings, and moisture content of affected materials. Without it, an adjuster has no reason to believe the equipment was necessary for the duration billed.
At DryMark Restoration Bellflower home, our technicians arrive with tablets pre-loaded with documentation templates. The photo record begins before we unload the first air mover. Every visit adds to the file. When we submit your invoice, the adjuster receives a package that answers questions before they’re asked.
The Haven Standard, Clause 1 requires a written price before work begins. But Clause 1 also requires that the price be supported by documentation that would survive audit. A price without proof is just a number.
How Bellflower’s Geography Affects Your Claim
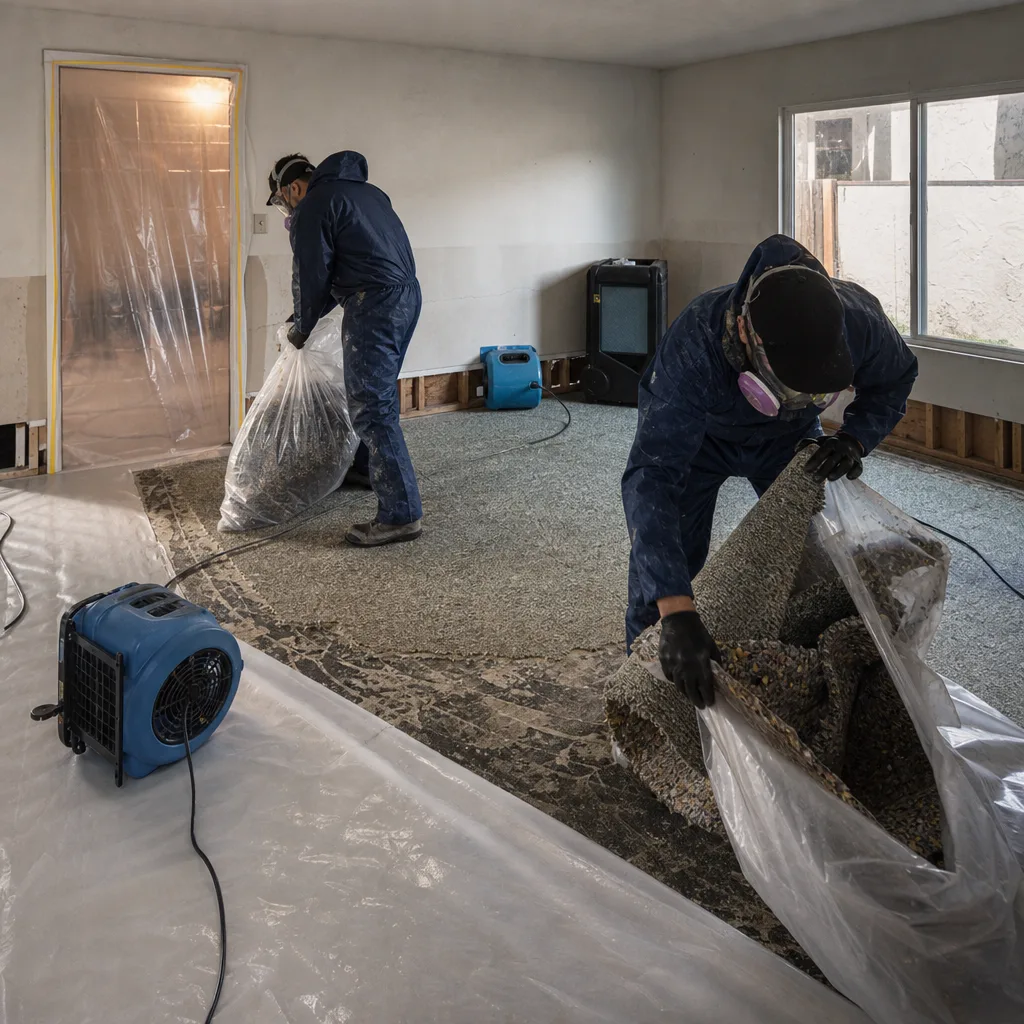
Bellflower sits at the edge of the Los Angeles River basin, and that geography - along with Damage Restoration Permits, Codes & Inspections in CA: What You Need to Know - changes how insurers classify your water source. Source classification determines whether your loss is covered at all, and at what limits.
Water damage falls into three categories under IICRC standards. Category 1 is clean water from a broken supply line. Category 2 is gray water with significant contamination - dishwasher discharge, washing machine overflow. Category 3 is black water: sewage, ground surface water, or any water that has passed through the ground before entering your structure.
Here’s where Bellflower’s location matters. Properties near the LA River basin, particularly in the southern and eastern portions of the city, are more likely to experience Category 3 flooding during heavy rain events. When the river channel overflows or storm drains back up, water that enters your home has contacted soil, debris, and possible sewage. Insurers classify this as ground water or flood water, and standard homeowner policies exclude it unless you carry separate flood coverage through the National Flood Insurance Program.
We’ve worked losses on Lakewood Boulevard where the source was initially reported as “rainwater intrusion” but was reclassified to Category 3 after adjuster inspection. The difference: whether the water entered through a roof defect (potentially covered) or through hydrostatic pressure against the foundation or slab (typically excluded without flood coverage).
Your documentation must establish the exact point of entry. Photos of the roof, gutters, window seals, and foundation walls taken immediately after the event can preserve a Category 1 or 2 classification that might otherwise default to Category 3. Once the water recedes, that evidence is gone.
Properties in the Rosecrans corridor and near the San Gabriel River western tributary face similar exposure. If you’re in these areas, we recommend photographing your foundation walls, sump pump installation, and any drainage improvements annually. After a loss, those photos become your proof of pre-event condition and maintenance.
Mitigation vs. Reconstruction: Why the Invoice Split Matters
This is the single most expensive confusion in restoration billing, and it costs Bellflower homeowners thousands.
Mitigation is emergency work: water extraction, demolition of unsalvageable materials, drying, sanitizing, and stabilizing the structure to prevent further damage. It’s urgent, often performed after hours, and billed at time-and-materials or unit pricing with equipment daily rates.
Reconstruction is the rebuild: new drywall, paint, flooring, cabinets, fixtures. It’s scheduled work, performed by carpenters and finish trades, and typically estimated as a fixed-scope project with line-item material and labor costs.
When these two phases appear on a single invoice, adjusters apply the reconstruction contractor’s overhead and profit rates to the entire bill - or they apply the mitigation contractor’s emergency rates to the rebuild. Either way, someone loses. Usually the homeowner, when the insurer caps payment at the lower of the two rate structures and the contractor balance-bills the difference.
The correct structure:
- Mitigation invoice: separate line items for extraction, equipment, monitoring, and demolition. Each day of drying documented with moisture readings proving progress. Equipment justified by psychrometric data showing when drying goals were achieved.
- Reconstruction invoice: separate scope with material allowances, labor hours, and finish specifications. Written price before work begins, per Haven Standard, Clause 1.
At DryMark Restoration Bellflower, we deliver two separate written scopes when both phases are needed. The mitigation scope is priced and signed before any equipment runs. The reconstruction scope is priced and signed only after the structure is dry and the full scope of rebuild is visible. No combined invoice. No rate confusion. No surprise balance billing after the adjuster pays based on the wrong contractor classification.
We’ve reviewed competitor estimates where a $4,200 mitigation bill and a $12,800 reconstruction bill were combined into a single $17,000 invoice with blended rates. The adjuster paid $11,400. The homeowner owed $5,600 out of pocket for work their policy should have covered. The error was structural, not substantive. The damage was real. The documentation was just formatted wrong.
What a Compliant Drying Log Looks Like
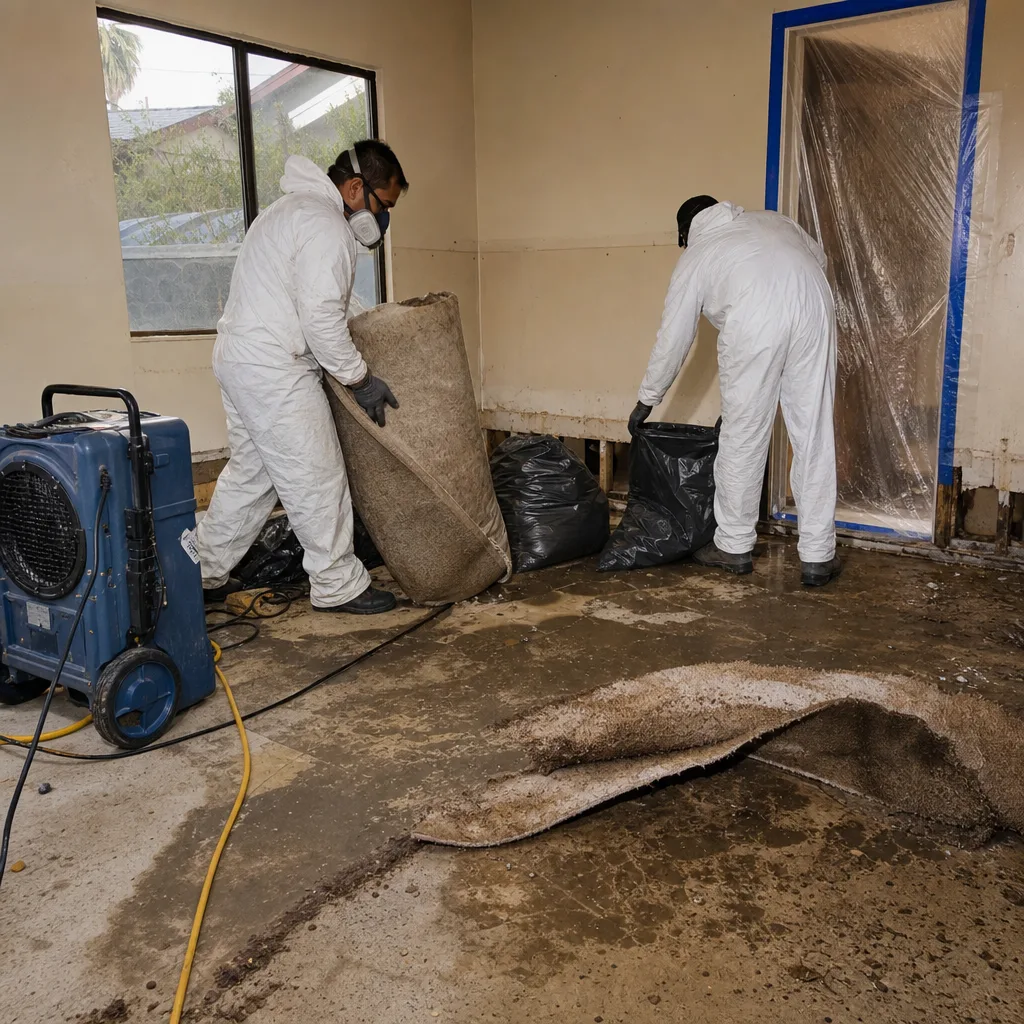
An adjuster reading your drying log is asking one question: was this equipment actually necessary for every day it was billed?
The answer must be in the numbers. Not in assurances. Not in brand names. In documented, comparable, daily measurements that show a trend from wet to dry.
Here’s what a room-by-room compliant drying log contains:
| Element | What It Is | Why the Adjuster Cares |
|---|---|---|
| Dry Standard | Moisture reading from an unaffected area of the same material in the same structure | Proves your “done” point is realistic, not arbitrary |
| Daily Moisture Content | Pin or non-invasive meter reading of affected material, same location each day | Shows progressive drying; justifies continued equipment |
| Temperature (°F) | Indoor air temperature at the dehumidifier intake | Affects evaporation rate; explains why drying takes longer in winter |
| Relative Humidity (%) | Percentage of moisture the air holds versus what it could hold at that temperature | High RH means dehumidifier is working; dropping RH means progress |
| Specific Humidity (GPP) | Grains of moisture per pound of dry air | The truest measure of moisture removal; unaffected by temperature swings |
| Vapor Pressure Differential | Difference in vapor pressure between wet material and surrounding air | Explains why air movers are positioned at specific angles and distances |
| Equipment Serial Numbers | Unique identifier for each dehumidifier, air mover, and specialty unit | Prevents double-billing; proves equipment was on-site |
Let’s make this concrete. A bedroom in a Bellflower ranch home on Woodruff Avenue floods from a supply line. Day 1: carpet and pad are extracted, baseboards removed, two air movers and one LGR dehumidifier placed. Moisture reading in drywall: 28%. Dry standard for this home’s drywall: 12%. The log shows 28%, 24%, 19%, 15%, 13%, 12% over six days. Temperature held at 74-78°F. Relative humidity dropped from 72% to 41%. Specific humidity fell from 92 GPP to 58 GPP.
That log justifies six days of equipment. Remove the daily readings and the adjuster has no basis to approve more than two days. The difference: roughly $340 per day in equipment charges, or $1,360 the homeowner pays if documentation fails.
Our crews use Dri-Eaz and Phoenix dehumidifiers with built-in data logging where available. The readings export directly to our job management system. No handwritten logs. No transcription errors. No gaps an adjuster can exploit.
Cross-Referencing Your Scope Against Policy Language
Before you sign any contractor’s scope of work, compare it to your policy’s covered-peril language. This single step has saved Bellflower homeowners from uncovered charges that appeared legitimate on the surface.
Most homeowner policies cover “sudden and accidental” water damage. The key exclusions to watch:
- Long-term leaks: damage that occurred over weeks, months, or years is typically excluded as maintenance-related
- Ground water and flood: requires separate flood coverage
- Sewer backup: may be excluded or limited to a specific dollar cap unless you purchased a rider
- Mold: often capped at $10,000 or excluded entirely unless it results directly from a covered water loss
When a contractor’s scope includes mold remediation but your policy excludes mold, you will pay that portion out of pocket unless the contractor can document that the mold growth began within 24-72 hours of a covered water loss and is inseparable from the mitigation. This requires specific language in the scope tying every mold-related action to the original covered event.
Similarly, if your policy covers “like kind and quality” replacement but the scope specifies upgraded materials - oak hardwood where you had laminate, for instance - the adjuster will pay for laminate and the contractor may bill you the upgrade difference. The Haven Standard requires that upgrades be noted as such with your written approval, not buried in a line item.
We provide a policy cross-reference checklist with every written scope. It maps each line item to the most common policy language that would cover it, flags potential exclusions, and notes where your specific policy terms may differ. Bring your declarations page. We’ll review it together before you sign.
Our Free Second Opinion on Any Written Estimate exists for exactly this situation. If another contractor has already provided a scope, we’ll review it against standard policy language at no charge. We’ve found $2,800 in uncovered charges on competitor estimates that the homeowner would have paid unknowingly.
Equipment, Standards, and What They Mean for Your Documentation
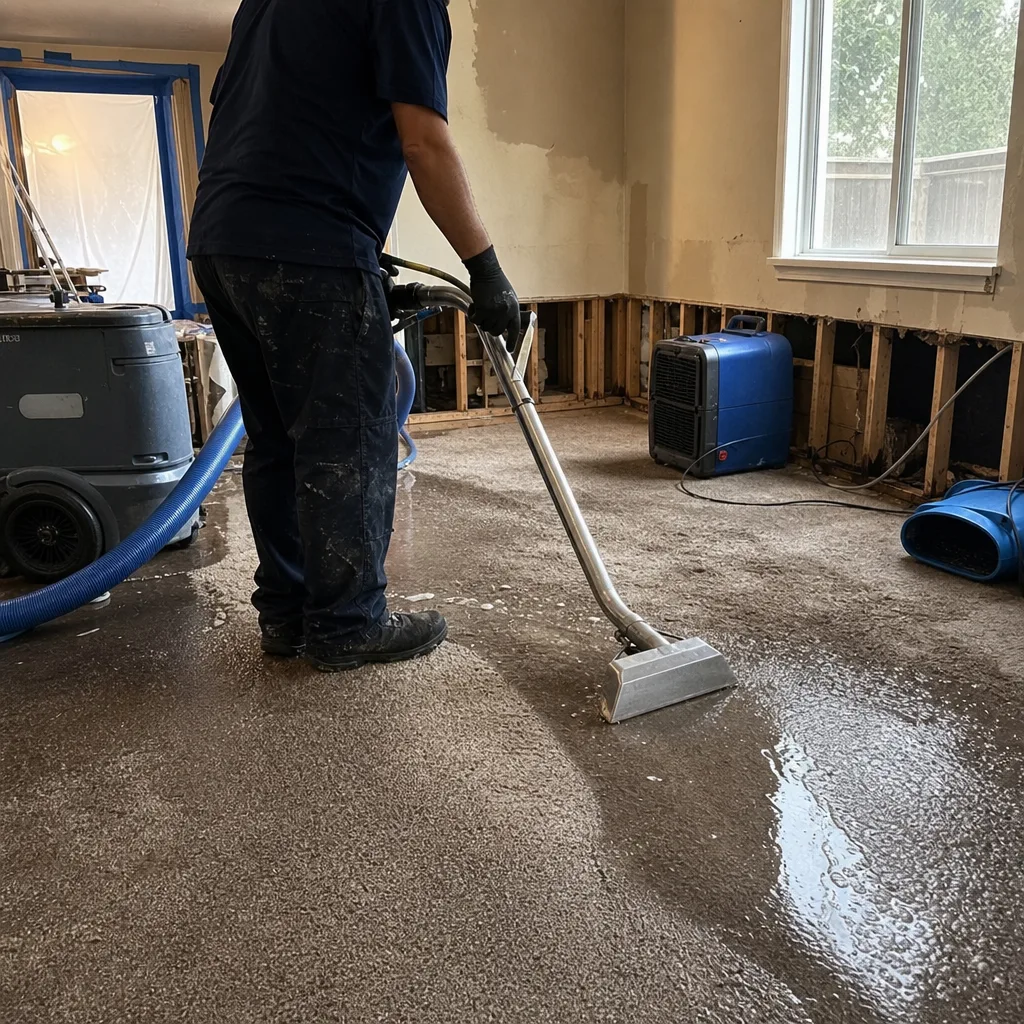
The equipment a restoration company deploys matters less than the documentation that equipment produces. A $4,000 Phoenix 200MAX dehumidifier and a box fan from the hardware store both move air. The difference is whether the output can be measured, logged, and presented to an adjuster as evidence of professional drying.
At DryMark Restoration Bellflower, we deploy professional-grade drying systems from Dri-Eaz, Phoenix, and XPOWER. These units are selected for their data output: the ability to record and export runtime hours, humidity levels, and temperature data that feeds directly into our daily drying logs.
But equipment is only as good as the standards it’s operated to. Our work is documented to three industry benchmarks:
- IICRC S500 - the standard for professional water damage restoration, defining categories of water, classes of destruction, and equipment calculations based on cubic footage and material permeability. An S500-compliant drying plan specifies exactly how many air movers and dehumidifiers are required for your specific loss class, not a guess based on “what we usually bring.”
- RIA (Restoration Industry Association) - guidelines for contractor conduct, documentation, and ethics. RIA membership requires adherence to continuing education and documented quality assurance.
- IFA (Indoor Air Quality Association) - standards for assessment and remediation of indoor environments, particularly relevant to mold and biohazard projects where air sampling and clearance testing are involved.
The critical output is not the equipment itself. It’s the daily drying log that combines equipment serial numbers, psychrometric readings, and moisture content measurements into a single document that proves professional standards were applied to your specific loss.
We’ve seen invoices from Bellflower-area contractors listing “professional drying” with no daily log, no moisture readings, and no equipment serial numbers. The adjuster paid extraction and demo only, denying $3,200 in equipment charges. The homeowner called us for a Free Second Opinion on Any Written Estimate - but the equipment was already gone, the structure was dry, and the documentation window had closed. The money was lost in the 72 hours after the loss, not in the loss itself.
Common Mistakes to Avoid
- Starting demolition before photographing the full extent of damage. Once drywall is removed, you cannot prove the water line height or the lateral spread through wall cavities. Photograph everything while wet, then demolish.
- Accepting a verbal estimate or “ballpark” figure. Haven Standard, Clause 1 exists because verbal pricing invites scope creep. Every job gets a written price before work begins, with no exceptions. If a contractor won’t put it in writing, the reason is usually not in your favor.
- Combining mitigation and reconstruction on a single invoice or contract. This creates rate confusion and gives adjusters a reason to cap payment at the lower contractor classification. Separate the phases, separate the scopes, separate the invoices.
- Ignoring Bellflower’s flood-source classification. Water from roof damage and water from ground intrusion are treated differently by insurers. Document the exact point of entry with photos before cleanup begins, especially in LA River basin-adjacent neighborhoods.
- Assuming mold is covered because water damage is. Mold coverage is often capped or excluded entirely. If your scope includes mold remediation, verify the contractor has tied every action to the original covered water loss with specific dates and documentation.
- Failing to get a second opinion on a competitor’s estimate. Our Free Second Opinion on Any Written Estimate has identified an average of $2,400 in problematic charges per review. The service is free because the documentation gap costs homeowners more than it costs us to review it.
- Letting equipment leave without final moisture readings. The last day of drying must be documented with readings at or below dry standard. If the crew pulls equipment and you have no final log, you have no proof the job was complete.
When to Call a Professional
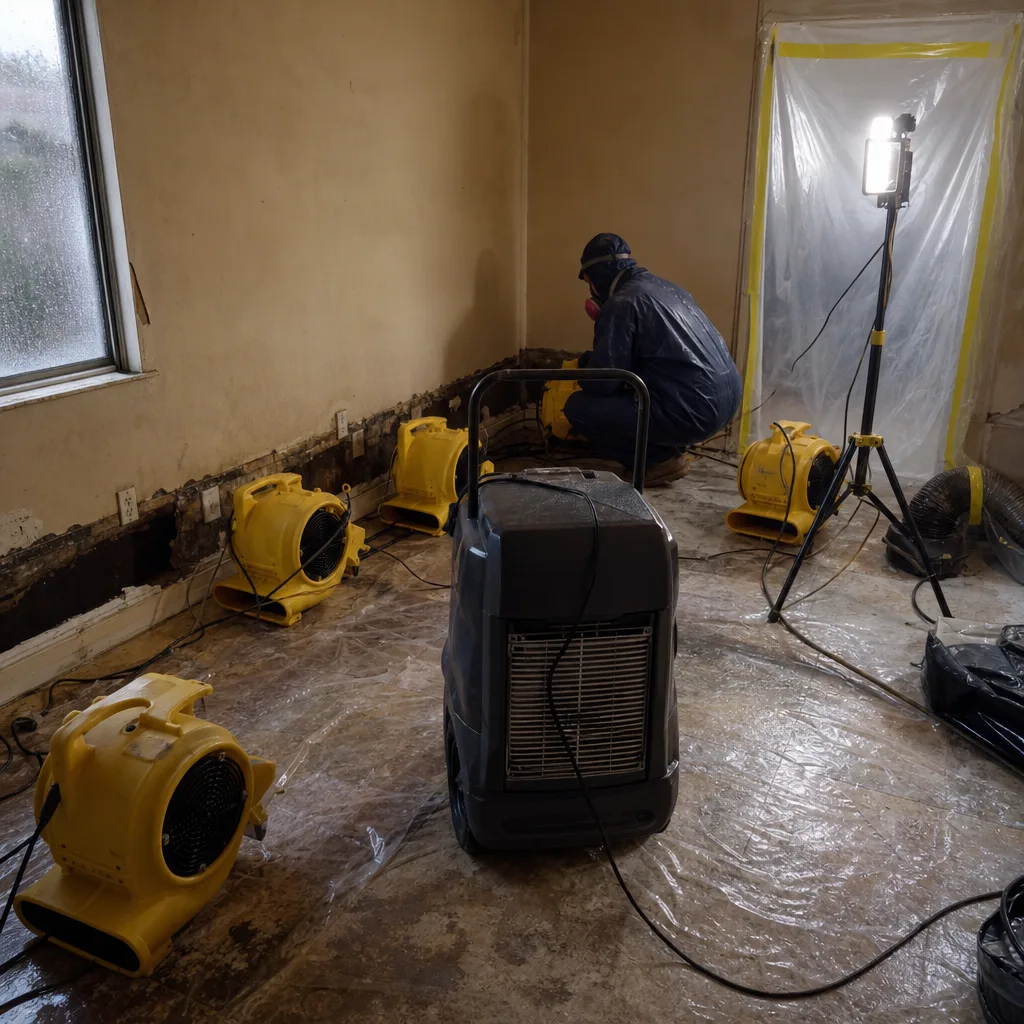
Call immediately when water is actively spreading, when you smell mold but cannot locate the source, when sewage is involved, when fire damage has compromised the structure, or when any damage event exceeds what you can document thoroughly yourself. The 72-hour documentation window does not pause for business hours.
Specific scenarios that require professional documentation from day one: water affecting more than one room, water that has been standing for more than 24 hours, any Category 2 or 3 water source, mold growth visible on more than 10 square feet, fire damage with structural compromise, and any loss where insurance coverage is uncertain.
In Bellflower, Water Damage Restoration in Bellflower and related services from DryMark Restoration Bellflower include live phone coverage 24 hours a day, 7 days a week with no voicemail on emergency lines. A live person answers every call. Technicians are background-checked, uniformed, and arrive with documentation systems ready.
DryMark Restoration Bellflower offers free estimates in Bellflower - call (424) 347-8338.
Frequently Asked Questions
Water damage mitigation in Bellflower typically ranges from $1,800 for a contained single-room extraction and drying to $8,500 for a whole-house Category 2 loss with extensive demolition and drying; see our Damage Restoration Cost Breakdown: The Bellflower Homeowner’s Reference for 2026 for detailed pricing factors. Reconstruction costs are separate and depend on finish selections, with drywall and paint averaging $3.50-$6.00 per square foot and flooring replacement ranging from $2.50 per square foot for laminate to $14.00 for engineered hardwood. Every job from DryMark Restoration Bellflower receives a written price before work begins, per Haven Standard, Clause 1. Call (424) 347-8338 for an exact quote - estimates are free.
Insurance covers sudden and accidental water damage from sources like burst pipes, appliance failures, and roof leaks in most standard homeowner policies. Coverage excludes long-term leaks, ground water intrusion, and flood water unless you carry separate flood insurance. The key factor is documentation: photos of the source, moisture readings, and a written scope that ties every action to the covered peril. Without this, legitimate claims are routinely reduced. We provide a policy cross-reference checklist with every scope to flag potential exclusions before you sign.
DryMark Restoration Bellflower maintains live phone coverage 24 hours a day, 7 days a week with no voicemail on emergency lines. For active water losses, we aim to have a technician on-site within 90 minutes of your call. The first 72 hours after damage are critical for documentation and drying setup, so same-day response directly affects both your structural outcome and your insurance claim. Call (424) 347-8338 - a live person answers every call.
Visible mold growth on less than 10 square feet of a hard, non-porous surface can sometimes be addressed with HEPA vacuuming and antimicrobial treatment by a trained technician. Growth exceeding 10 square feet, mold inside wall cavities, or any mold resulting from Category 2 or 3 water requires full remediation with containment, negative air pressure, and clearance testing. The deciding factor is not appearance but location and source: hidden mold and sewage-related growth require professional remediation to protect occupant health and satisfy insurer requirements. Mold Remediation in Bellflower from DryMark Restoration Bellflower includes documented containment photos and air clearance reports.
A mitigation scope covers emergency stabilization: water extraction, demolition of unsalvageable materials, drying, and sanitizing. It’s urgent work billed at time-and-materials or unit pricing with daily equipment rates. A reconstruction scope covers the rebuild: new drywall, paint, flooring, fixtures. It’s scheduled work with fixed-scope line-item pricing. Combining them on one invoice creates rate confusion that adjusters exploit to reduce payment. We deliver separate written scopes for each phase, each with its own price signed before work begins.
At DryMark Restoration Bellflower, we coordinate directly with your adjuster, providing the photo record, daily drying logs, written scope, and equipment justification that supports your claim. We do not ask you to negotiate pricing or coverage. Our documentation package is designed to answer adjuster questions before they’re asked, reducing delays and disputes. You remain informed at every step, but the paper chase is ours to manage. This documentation-first approach is why we can offer the 365-Day Done Right Promise under The Haven Standard - the work is provable, not just promised.
The Bottom Line
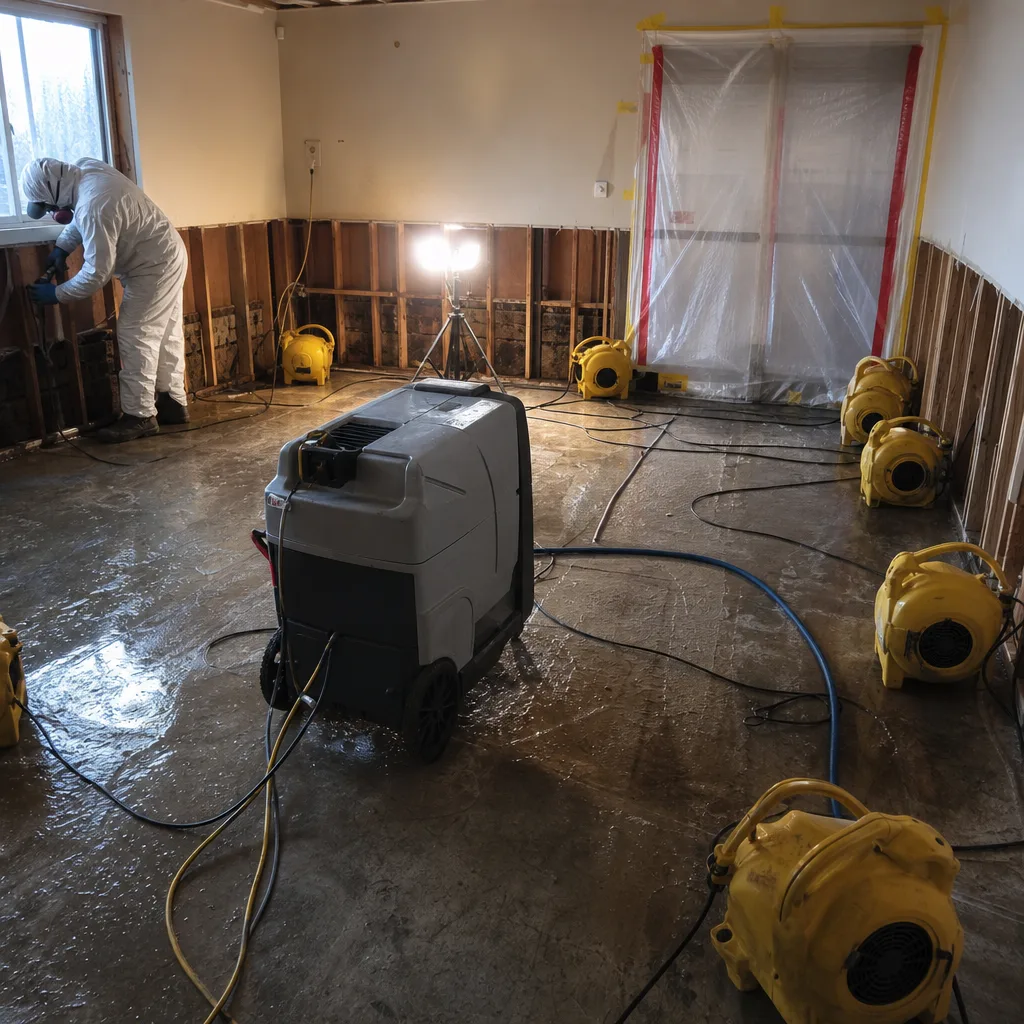
The money you lose in a restoration project is rarely lost to the damage itself. It’s lost in the 72 hours after, when undocumented decisions become unprovable claims. In Bellflower, where LA River basin flooding can reclassify your water source and where combined mitigation-reconstruction invoices trigger automatic payment reductions, documentation is not paperwork. It’s the work.
Get the photos before the demo. Get the moisture readings before the equipment runs. Get the written scope before you sign. Cross-reference that scope against your policy’s covered-peril language. Separate your mitigation invoice from your reconstruction invoice. And if a contractor won’t put a price in writing before work begins, find one who will.
At DryMark Restoration Bellflower, every job since 2011 has started with a written price, proceeded with a documented record, and ended with a signed warranty under The Haven Standard. The 365-Day Done Right Promise means if it’s not done right, we make it right. Not because we say so. Because we can prove what was done, when, and to what standard.
Call (424) 347-8338 for a free estimate. A live person answers, 24 hours a day, 7 days a week. Or bring any competitor’s written estimate for a Free Second Opinion - we’ll review it at no charge and show you what the documentation should look like.
Written by Alicia Brennan, Owner at DryMark Restoration Bellflower, serving Bellflower since 2011.